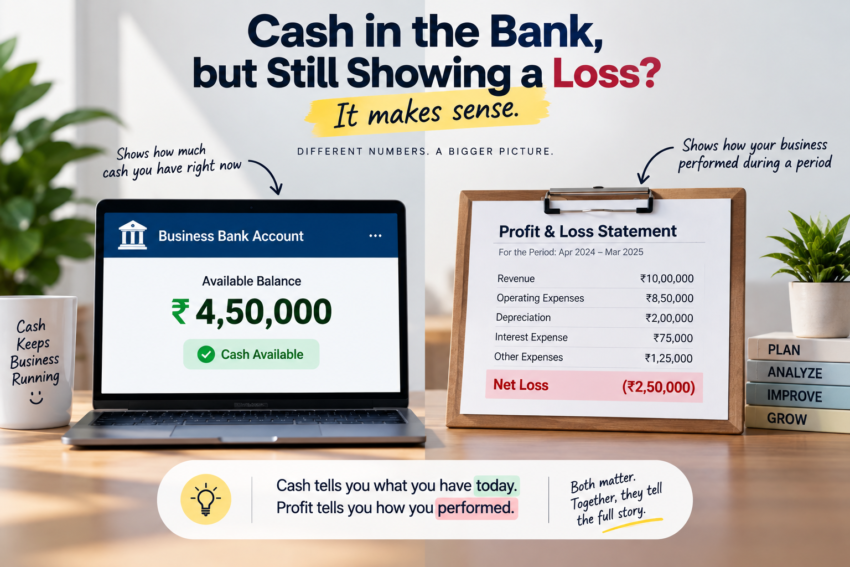
Have you ever looked at your business bank account and thought, “We have plenty of cash—so why does the Profit & Loss Statement show a loss?”
You’re not alone.
This is one of the most common areas of confusion for business owners, especially when reviewing financial statements. The key is understanding that cash and profit are not the same thing.
Your bank account tells you how much cash your business has available at a particular point in time. Your Profit & Loss (P&L) Statement tells you how much revenue your business earned and how much expense it incurred during a specific accounting period.
Once you understand this distinction, the numbers start making much more sense.
Cash vs. Profit: What’s the Difference?
Think of it this way:
Cash = What is available in the bank
Profit = Revenue earned − Expenses recognized
A business can have cash in the bank and still report a loss.
For example, imagine a business starts the month with $50,000 in its bank account. During the month, it earns $20,000 in revenue but records $30,000 of expenses.
The business has made a $10,000 accounting loss.
But it may still have significant cash in the bank because the opening $50,000 did not necessarily come from this month’s profits.
It could have come from:
- Previous periods’ cash
- Owner contributions
- Business loans
- Customer deposits or advance payments
- Other financing activities
This is why looking at the bank balance alone does not tell you whether a business is profitable.
7 Reasons Your Business Can Have Cash While Showing a Loss
1. Your Business Started With Cash
Your current bank balance includes money carried forward from previous periods.
Suppose your business starts the year with $100,000 in cash and records a $20,000 loss during the year.
The business could still have cash remaining.
The loss reduces profitability and, ultimately, equity, but it does not automatically mean the bank account must fall to zero.
2. You Received a Business Loan
A loan can significantly increase your bank balance without increasing your revenue.
For example:
Before loan: $30,000
Loan received: $70,000
Bank balance: $100,000
The business now has $100,000 in cash, but the $70,000 loan is generally recorded as a liability, not income.
The principal repayment also generally does not appear as an operating expense on the P&L.
However, interest expense is generally recognized in the P&L.
This is a classic example of why financing transactions should not be confused with business revenue.
3. The Owner Invested Money Into the Business
An owner may transfer personal funds into the business bank account.
For example, an owner contributes $25,000 to help fund business operations.
The bank balance increases by $25,000, but this does not mean the business generated $25,000 of sales.
Instead, the transaction generally affects owner’s equity or contributed capital.
So, once again:
More cash ≠ more revenue
4. Revenue and Cash Collections Happen at Different Times
Under accrual accounting, revenue is generally recognized when it is earned—not simply when cash is received.
Imagine your business completes $50,000 of work and invoices the customer.
The business may recognize revenue and record:
Accounts Receivable — $50,000
But if the customer has not paid yet, the $50,000 will not be sitting in the bank.
The opposite can also happen.
If a customer pays in advance, the business may receive cash before the related revenue is earned. Depending on the circumstances, the amount may initially be recorded as a liability such as deferred revenue, rather than immediate revenue.
This is one of the reasons timing differences matter so much in accounting.
5. You Purchased a Long-Term Asset
Imagine your business purchases equipment for $40,000.
Your bank account decreases immediately.
But you generally don’t recognize the entire $40,000 as an expense immediately if the equipment is a capital asset.
Instead, the equipment is recorded on the Balance Sheet as an asset, and its cost may be allocated to expense over its useful life through depreciation.
So you could have:
Cash decreases → Asset increases
without an equivalent immediate reduction in P&L profit.
This is an important distinction between cash movement and expense recognition.
6. Depreciation Reduces Profit Without a Current Cash Outflow
Depreciation is another major reason a business can show a loss while still having cash.
Suppose a company records $15,000 of depreciation expense during the year.
That depreciation reduces accounting profit.
But there is no $15,000 cash payment when the depreciation entry is recorded.
This is because the cash outflow generally occurred when the asset was originally purchased.
Therefore:
Depreciation can reduce P&L profit without reducing the current bank balance.
7. Some Expenses Have Been Incurred but Not Yet Paid
Accrual accounting also works in the other direction.
Suppose a business receives a $10,000 professional-services bill in December but pays it in January.
If the expense relates to December, it may be recognized in December even though the cash leaves the bank in January.
The result?
December P&L: Expense recognized
December bank account: No corresponding cash payment yet
This is known as an accrual.
A Simple Example
Consider the following simplified business scenario:
| Transaction | Amount |
|---|---|
| Opening cash balance | $50,000 |
| Customer collections | $30,000 |
| Operating expenses paid | ($35,000) |
| Equipment purchased | ($20,000) |
| Loan received | $40,000 |
| Loan principal repaid | ($5,000) |
| Depreciation expense | ($10,000) |
The bank balance and the P&L will not tell the same story because they measure different things.
The P&L focuses primarily on:
Revenue − Expenses = Profit/Loss
The bank account reflects:
Opening Cash + Cash Inflows − Cash Outflows = Ending Cash
Some transactions affect cash without directly affecting P&L profit, while some P&L expenses do not create an immediate cash outflow.
So, Which Statement Should You Look At?
The answer is: all of them.
A complete financial review usually involves looking at three key statements.
1. Profit & Loss Statement
Answers:
“Did the business make a profit or loss during this period?”
It summarizes revenue, expenses, and resulting profit or loss.
2. Balance Sheet
Answers:
“What does the business own and owe at a specific date?”
It shows:
Assets = Liabilities + Equity
3. Cash Flow Statement
Answers:
“Where did the business’s cash come from, and where did it go?”
Cash flows are generally analyzed through:
- Operating activities
- Investing activities
- Financing activities
Looking at all three statements together provides a much clearer picture of financial performance and financial position.
What Should You Check When the Numbers Don’t Seem to Match?
If your business has cash but your P&L shows a loss, review:
Revenue & Receivables
- Are all sales recorded?
- Are there outstanding customer invoices?
- Are any customer payments recorded incorrectly?
- Are advance payments being treated correctly?
Expenses & Payables
- Are there unpaid bills?
- Have accruals been recorded?
- Are prepaid expenses being recognized in the correct periods?
Assets
- Were equipment or other fixed assets purchased?
- Is depreciation being recorded correctly?
Financing
- Were loans received?
- Were loan principal payments made?
- Was interest recorded separately?
Equity
- Did the owner contribute funds?
- Were there owner withdrawals or distributions?
Bank & Bookkeeping
- Are all bank transactions recorded?
- Are there duplicate transactions?
- Are transfers between bank accounts properly classified?
- Is the accounting period correct?
- Has the bank account been reconciled?
The Bottom Line
A healthy bank balance does not automatically mean a business is profitable. Likewise, a P&L loss does not automatically mean the business has run out of cash.
Cash measures liquidity.
Profit measures financial performance over an accounting period.
That is why a business can have:
Profit + Cash
Profit + Low Cash
Loss + Cash
Loss + Low Cash
Each combination can occur for different accounting and business reasons.
The real question isn’t simply:
“How much money is in the bank?”
It is:
“How did the business generate its cash, where did the cash go, and how does that compare with its reported financial performance?”
Understanding the relationship between the P&L, Balance Sheet, Cash Flow Statement, and bank activity is essential for making informed financial decisions.
If your numbers don’t appear to make sense, a detailed reconciliation can help identify whether the difference comes from timing differences, financing, asset purchases, accruals, non-cash expenses, owner transactions, or bookkeeping errors.
Cash tells you what you have available today.
Profit tells you how the business performed.
Together, they tell a much more complete story.